The adjuster is coming Tuesday. The tarp has been on since the storm, you have sixty photos on your phone, and the roof was already 26 years old before the wind got to it. This site connects you by phone with an independent local roofing contractor who documents roof damage in north Brevard County. This site is not an insurer, a law firm, or a public adjuster, and none of what follows should be read as legal advice.
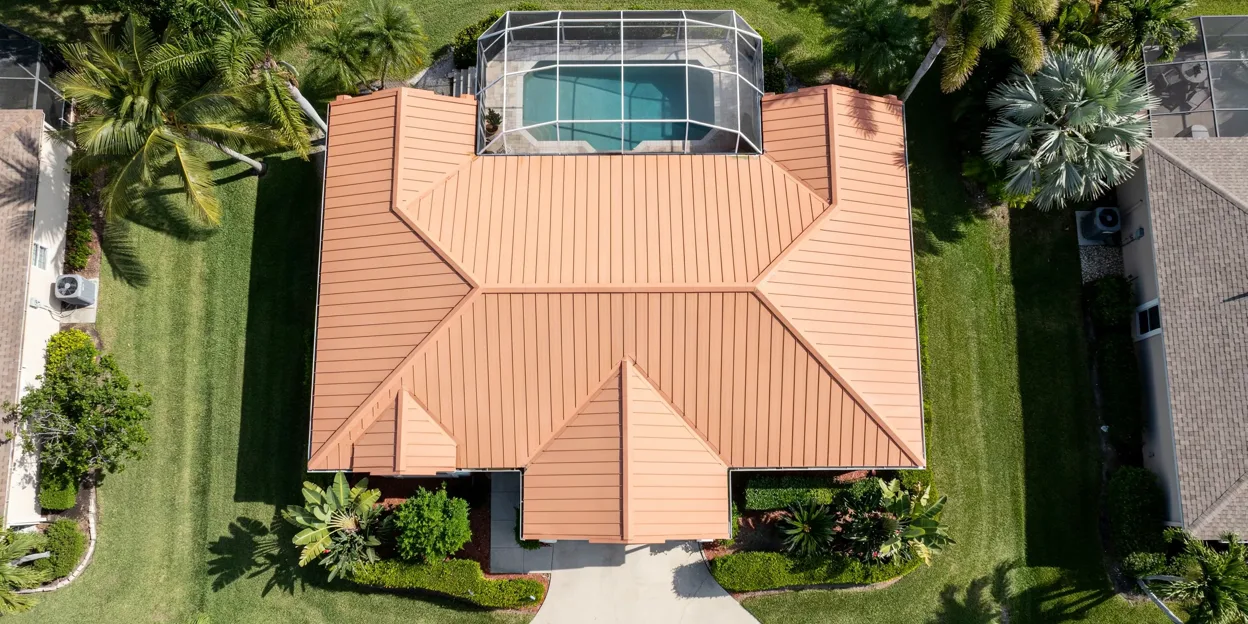
In a claim, what the contractor contributes is a record. They walk the roof and photograph each slope, count damaged shingles or panels, note where underlayment is torn, and check whether the boards under the opening are wet. They separate what the storm did from what was already worn, and on a 1990s roof over a 1960s deck that separation is the whole claim. From that, they build a scope, line by line: the materials, how much of each, the labor, the permit, and whatever has to be removed to reach the damaged part.
Many contractors will meet the adjuster on the roof so both are looking at the same thing. What they do not do is promise what the insurer will pay, and a contractor who does is telling you something they cannot know.
Take pictures of the damage, inside the house and out on the roof, before you move a thing. Get the roof tarped and keep the receipt; emergency protection is normally part of a claim, and your policy requires you to prevent further damage. Then phone your carrier and have a claim number assigned.
Then find the declarations page and read three lines: the hurricane deductible, usually 2 to 5 percent of dwelling coverage on a named storm; the notice-of-claim deadline; and whether the roof is covered at replacement cost or actual cash value. A roof over a certain age on an actual-cash-value schedule pays out less, and on a Titusville roof from the 1990s that is worth knowing before Tuesday.
No one answering this line can say what your carrier will pay on your claim. Broadly speaking, Florida homeowner policies exist to cover a roof that a storm's wind tore up overnight. Wear, age, gapped decking, and a leak that has been running since Irma are usually treated as maintenance and excluded. On an older roof the adjuster's question is whether the storm caused the damage or found it, and the contractor's photos and scope are what answer that.
Once the insurer issues its decision, the repair is a storm damage or replacement job with a permit pulled through the city or the county. A disputed claim is a job for a licensed public adjuster or an attorney, not a roofer, and the state's Division of Consumer Services runs a helpline and a mediation program for property claims.
Florida rewrote its property insurance law in December 2022. The window to report a new claim shrank from two years to one year after the date of loss, and a supplemental claim has to be filed within 18 months. Assignment of benefits, where a contractor takes over your claim, is not allowed on residential policies issued on or after January 1, 2023, so the claim stays in your name. And since May 2022 a carrier cannot refuse to renew solely for roof age if the roof is under 15 years old or an inspection shows five or more years of life left.
The Florida Office of Insurance Regulation publishes the wind-mitigation form (OIR-B1-1802) that carriers price from, and a new roof documented on that form is often what changes a renewal quote. Many north Brevard homeowners who lost private coverage after the 2004 storms or after Irma ended up with Citizens Property Insurance, the state-backed carrier, which has its own roof-age and inspection rules at renewal.
Nothing helps a claim more than a roof inspection report dated before the storm, because it shows the adjuster the condition of the roof the week before the wind came.
Be ready with the property address, the date of the storm, your claim number, the day the adjuster is due if one is booked, and the declarations page from your policy. Say the year of the roof and whether it is tarped. Call (321) 490-0701.
 Taking requests
Say it in plain words. The call is routed to an independent local roofing contractor who works shingle, metal, and flat roofs on the older homes and rural lots of north Brevard County.
A lifted shingle, a rusted valley, a split pipe boot, or a drip that shows up with every afternoon storm, traced to its source and fixed.
Tear-off to the deck, plank boards checked and replaced where soft, new underlayment, and a new roof permitted through the city or Brevard County.
Tarping, photos, and repair after wind off the lagoon, a fallen oak, or a named storm crossing the Space Coast opens the roof.